

Why Subscription Businesses Are the New Chargeback Bullseye & How Optimizing Payment Infrastructure Can Help
For years, subscription and recurring-billing businesses tended to have one quiet advantage in the chargeback fight: low ticket size.
A $9.99 monthly charge simply wasn’t the kind of transaction that triggered disputes. Chargebacks skewed toward big-ticket purchases and classic buyer’s remorse — the $400 electronics order, the $200 hotel booking gone wrong. Recurring billing sat comfortably outside that pattern.
That advantage is disappearing.
According to the 2026 Chargeback Field Report, the average disputed transaction is now $94. That’s smaller than the average overall transaction of $100. Disputes are no longer concentrated in high-ticket purchases; they’re increasingly coming from routine, low-value transactions. For subscription businesses, that’s not a peripheral trend. It’s a direct hit to the assumption that small charges are safe charges.
Recommended reading
- Dispute Apple Pay Transaction: How Does The Process Work?
- What is Alipay? Can US Consumers & Merchants Use Alipay?
- Terminal ID Number (TID): What is it? What Does it Do?
- Agentic Commerce Is Coming. Who Owns the Consequences?
- What Are Credit Card Networks? What Do Card Networks Do?
- How Do QR Code Payments Work: Critical Info & How to Accept
The Data Points Directly at Recurring Billing
This isn’t just an inference from a single statistic. The same report identifies subscription billing as the single most cited chargeback risk factor among merchants, ahead even of operating in a “high-risk” industry. Nearly a third of merchants say it’s a primary source of dispute exposure.
Layer on a few more findings, and the picture becomes clear:

Reminder Gaps are Common
Chargebacks911 also reports that among merchants who offer recurring payments, more than a quarter don’t remind cardholders before or after billing. Another 17% only send post-charge reminders which do little to prevent disputes.
Descriptor Confusion is Widespread
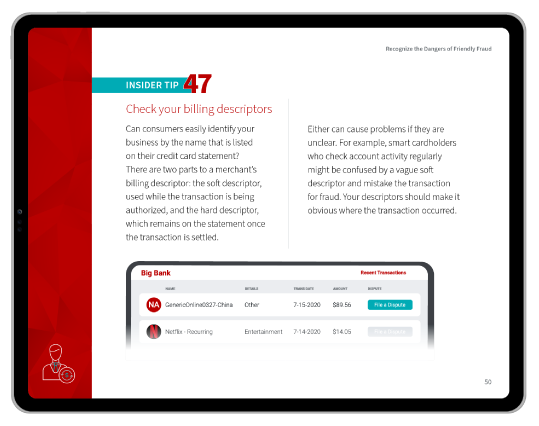
Only about half of merchants say they know exactly how their billing descriptor appears on a customer’s card statement. A cryptic or unrecognizable descriptor next to a small, forgotten subscription charge is a textbook trigger for an “I don’t recognize this charge” dispute filed with the bank instead of the merchant, because the bank is faster and easier to reach.
Chargeback Culture is Normalizing
The same report notes that filing a dispute has become easier than ever and often involves less friction than the checkout itself. For a customer who’s forgotten about a subscription, disputing is now the path of least resistance; faster than finding a cancellation button.
None of these risk factors are new. What’s new is that they’re converging with a market-wide shift toward smaller, more frequent disputes which means the small blind spots recurring billing has always had are no longer small.
Why This Belongs in the Payments Conversation, Not the Fraud Conversation
It would be easy to file this under “fraud team problem.” But look closely at the drivers above — reminder timing, descriptor clarity, and notification cadence. None of them are fraud detection issues. They are payment infrastructure issues. They live in the billing and processing layer, not the risk-scoring layer.
That distinction matters, because it changes who’s responsible for fixing it and what the fix looks like:
#1 | Pre- & Post-Charge Notifications Built Into the Billing Flow
A simple heads-up before a recurring charge and a clear receipt afterwards closes the exact gap the data shows. Merchants who skip these notifications are handing cardholders a reason to call their bank instead of remembering the subscription.
#2 | Billing Descriptors That Actually Describe the Purchase
If half of merchants don’t know what their own descriptor looks like on a statement, that’s not a fraud prevention gap; it’s a payment configuration gap. Descriptors should be recognizable enough that a customer sees the charge and immediately remembers the service, brand, and reason for the payment.
#3 | Retry & Dunning Logic That Doesn’t Look Like a Surprise Re-Charge
Failed payment retries are a normal part of subscription billing, but a retry that arrives without warning can look identical to an unauthorized charge from the cardholder’s perspective. An unexpected retry can feel like the merchant charging them without permission, which pushes some people toward “dispute first, ask questions later” instead of contacting support. Retry logic needs the same notification discipline as the original charge.
#4 | Account Updater for Expired or Reissued Cards
When a card is reissued, a subscription charge that used to be familiar can suddenly look unfamiliar. An account updater solution that refreshes card data in the background prevents this false alarm before it becomes a dispute. Updating the card data automatically avoids a retry altogether.
#5 | Easy, Visible Pause & Cancellation Options
Most friendly fraud comes down to convenience: it’s easier to tap “dispute” in a banking app than to track down a cancel button buried in account settings. A pause or skip-a-month feature closes that gap, giving subscribers a middle ground instead of an all-or-nothing choice. And it costs far less than a chargeback and re-acquiring that customer later. The easier it is to pause a subscription, the less tempting it becomes to dispute it.
The shrinking average transaction amount for chargebacks isn’t just a fraud trend for subscription and recurring-payment businesses to monitor from a distance. It’s a direct reflection of how the payment experience is built.
The businesses best positioned to weather this shift aren’t necessarily the ones with the most aggressive fraud filters. They’re the ones whose payment infrastructure — notifications, descriptors, retries, card data — gives cardholders every reason to recognize a charge, and no reason to dispute it.