



Unmasking Address Fraud: How to Spot it — & Stop it — Once & for All
A customer contacts you about an order they say never arrived. You pull the record, and the billing address matches the issuer’s file, with nothing else about the order out of place. The card was real, the address was real, but the person holding neither of them collected the package.
That is what address fraud looks like from your side of the counter. It rarely arrives as an obvious bad order, because the address is the part the fraudster took care to get right.
In this post, we’ll look at how address fraud works, what it gets past at checkout, and what to check before you ship.
Recommended reading
- BIN Attack Fraud: How the Scam Works & How to Prevent It
- Credit Card Shimmers: Are You Prepared for “Skimming 2.0?”
- How to Identify & Prevent Shipping Scams in 2026
- What are Reshipping Scams? Can Victims Actually Go to Jail?
- How Generative AI Could be Used to Weaponize Chargebacks
- How to Prevent Affiliate Fraud: Top Tips for 2026
What is Address Fraud?
- Address Fraud
Address fraud is the use of someone else’s real address, or a fabricated one, to obtain credit, goods, services, or cover. Address fraud enables other fraudulent behaviours, like redirecting goods purchased by an authorized user to the fraudster’s address.
[noun]/ǝ • dres • frôd/
Address fraud is a type of identity theft that occurs when a fraudster uses someone else’s physical mailing address, or even a fake address, to facilitate illegal activities.
This can include obtaining credit, goods, or services under false pretences. It can also apply to other criminal schemes, though. In essence, it could involve any case of fraud that’s dependent on a fake address: opening a bank account, school enrolment, insurance schemes, etc.
This often happens when a criminal impersonates someone else to redirect that person’s mail. One route is a change of address filed with the Postal Service in the victim’s name, which sends the victim’s mail to an address the fraudster controls.
Address fraud can impact both consumers and merchants, resulting in financial loss and reputational damage for both parties. Resolving the situation is a long, time-consuming process.
USPS now requires identity verification on every change of address request. This added an extra layer of security and made address fraud more difficult. However, dedicated fraudsters can still easily defeat this layer of security.
Why Would a Fraudster Want Your Customer’s Address?
An address on its own is not worth much to a fraudster. What it is worth depends on what it is paired with, and the pairing that matters to you is a stolen card number.
Card-not-present (CNP) fraud has one persistent problem: the validation devices at checkout are looking for a mismatch. The address verification service (AVS) compares the numeric portion of the billing address against the issuer’s file. A fraudster holding the cardholder’s genuine billing address supplies it and clears the check, because there is no mismatch there to find.
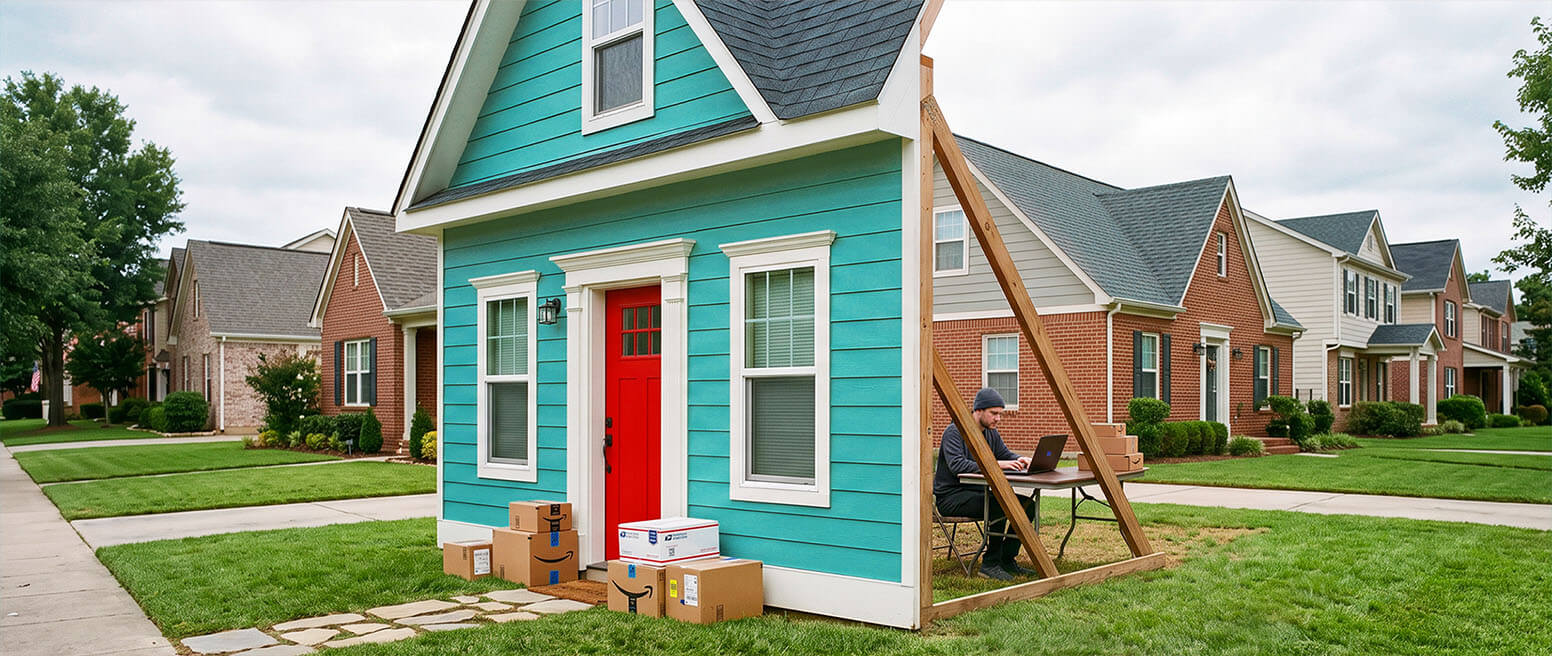
What is left is the question of where the goods actually go. Some fraudsters ship to the billing address and intercept the package before the cardholder sees it. Others already control an address, through a mail forwarding order or a rented mailbox, and route the goods to it instead.
Either way the order that reaches you looks correct, because the part your tooling can check is the part that is true. I hear this described as a tooling failure more often than it actually is one. The check did what it was built to do, and the address was never the lie.
A stolen card is rarely just a number. The people who buy them buy the whole record: the cardholder’s name, the billing address, sometimes the security code and the date of birth. Every field a merchant asks for, the fraudster already has.
Every field matched.
The order was still stolen.
AVS checks the order against the bank’s file. It cannot check it against the person holding the card.
-
1
An order lands at 2:14 in the morning.
Real name. Real card. Real billing address. All three stolen from the same person.
Order #48120 $1,284.00- Name
- Marta Okonjo
- Card
- Visa •••• 4417
- Billing
- 1180 Ridgeview Rd, FL 34689
Approved in nine seconds. -
2
The address check runs.
It compares two things, and only two: the street number and the postal code.
Typed into your checkoutMarta Okonjo
1180 Ridgeview Rd
Palm Harbor FL 34689
On file at the issuing bankMarta Okonjo
1180 Ridgeview Rd
Palm Harbor FL 34689
AVS response Y. Street number and postal code both match.
PassNothing in this test can fail. The details are genuine. Only the hands holding them are not.
-
3
The goods go out.
Delivery goes to an address the check was never shown.
-
4
Day 41. Marta reads her statement.
She has never heard of your store. Her bank opens the dispute the same afternoon.
Order #48120 · your store
Reason 10.4 · Other Fraud, Card Absent Environment
$1,284.00
Not authorized -
5
The money leaves.
The funds are pulled back out of your account. The goods left the building six weeks ago.
Your accountSale, settled+ $1,284.00Chargeback− $1,284.00Dispute fee− $25.00Merchandise, unrecoverable− $1,284.00Net− $1,309.00Forty-one days to lose it.
AVS proves the address is real. It never proves the buyer is.
This is why a full AVS match is evidence of nothing on its own. It confirms that the address given matches the address on file. It says nothing about who typed it, and the merchant is the only party in the chain that pays when the answer turns out to be wrong.
How Does Address Fraud Work?
There are a lot of different practices that fall under the umbrella of address fraud. The exact scheme depends on the fraudster's intentions and the specific type of address fraud being executed. However, the steps and methods criminals might use to commit address fraud generally go as follows:


Discover new startegies to eliminate fraud and protect your revenue
Request a Demo
Common Examples of Address Fraud
So, we’ve got a basic rundown of how these attacks are often conducted. However, address fraud can manifest in various forms, each with its unique set of methods and goals. What are some specific address scams that readers should know about?
The following are some of the most common types of address fraud that individuals and businesses may encounter:
What’s the angle behind using my address?
by u/Strange-Marzipan9641 in Scams
Someone Is Claiming They Live At Our Address
by u/SaraPortland1 in legaladvice
Address Fraud? Advise what to do!
by u/emptyboat_ in Scams
What is a Change of Address Scam?
A change of address scam redirects someone’s mail to an address the fraudster controls. Filed with USPS in the victim’s name, it results in everything addressed to the victim on paper — card statements, replacement cards, account notices, anything else the victim was waiting to read — being directed to the perpetrator.
It’s worth being precise about how that filing works now, because it changed, while most descriptions of this scam did not.
A change of address request once only needed a name, an old address, and a signature. Current USPS rules require identity verification on every request, though. Online, that means phone-based identity proofing plus a small card payment whose billing address has to match either the old address or the new one. Where the online check fails, the request has to be finished in person with photo identification. The Postal Service also mails two letters: a move validation letter to the old address, and a customer notification letter carrying a confirmation code to the new one.
Changing addresses? USPS sends address fraud safeguards to both ends of the move.
Move Validation Letter
Tells whoever is still there that a move was filed. It warns. It cannot undo anything.
Confirmation Notification
Carries the confirmation code. That code edits or cancels the request.
Only one of the two addresses is somewhere the person who filed has to be. The letter that can stop the move goes to the other one.
The problem is that a fraudster already holding the victim’s card details can satisfy the card check, because the billing address on that card is the old address the form is asking about. The verification step filters out opportunistic identity thieves, but it leaves the dedicated fraudsters who have already done the harder work.
For you, the part that matters is the sequence, rather than the filing. A customer whose mail has been redirected stops receiving statements and notices, which means they stop noticing charges. The dispute then arrives later than it otherwise would, and it arrives with less of the transaction remembered. By the time it reaches you, it’s a chargeback about an order that shipped months ago.
Consequences of Address Fraud for Consumers
As I alluded to in the last section, address fraud can have wide-ranging and severe consequences for both consumers and merchants. On the consumer side, those whose personal information is used to facilitate address fraud will bear the initial costs of the scam:
Consequences of Address Fraud for Merchants
So, the target of the fraud bears the up-front costs. In the end, though, most costs end up getting passed along to merchants through the dispute process, along with other consequences:
Whichever way you slice it, address fraud is bad news for everyone. That said, how can consumers and merchants tell when they’ve been targeted? And, what can members of either group do to stop it?
Save time. Prevent fraud. Fulfill more orders.
Request a Demo
Address Fraud Warning Signs for Businesses
Merchants must also be vigilant in identifying potential address fraud, as it can lead to financial losses and reputational damage. The following are some warning signs that may indicate address fraud from a merchant's perspective:
- Multiple Orders to the Same Address: Receiving multiple orders from different customers shipping to the same address is a red flag, especially if the items ordered are of high value or easily resold.
- Address Mismatches: When a customer's billing and shipping addresses don't match, or the shipping address is in a different country.
- Unusually Large Orders: Large orders that are inconsistent with a customer's typical purchasing behavior, particularly if the orders involve high-value items or express shipping.
- Multiple Payment Methods: If a customer uses multiple credit cards or payment methods to complete a single transaction or a series of transactions.
- Transaction Velocity: A series of transactions made in quick succession from the same IP address or using the same shipping address.
- Customer Complaints: If you receive customer complaints about not receiving their orders or if the orders were shipped to the wrong address, this may indicate address fraud.
- “High-Risk” Destinations: Be cautious of orders shipping to destinations known for high rates of fraud or where reshipping services are prevalent.
- Unusual Shipping Requests: Watch for customers who request shipping to a third party, such as a "friend" or "relative," or who ask for packages to be left in a specific location rather than delivered to the shipping address.
This list is by no means exhaustive. There are seemingly infinite ways in which mailing addresses and credentials can be used against consumers, merchants, and financial institutions. But how can potential victims protect themselves and their businesses in the long term?
Preventing Address Fraud
Merchants are rarely the direct target of an address fraud scheme. However, they face financial impacts like chargebacks for purchases that never arrive at the cardholder’s doorstep.
It doesn’t matter whether an attack is centred on an individual or business. In either case, awareness and planning are excellent ways to prevent address fraudsters from succeeding. Though no practice on the merchant’s end can fully eliminate exposure to address fraud, there are steps that can help reduce your risk. I suggest that merchants:
#1 | Implement Strong Authentication Measures
AVS, multi-factor authentication, and 3-D Secure are often grouped together, and they do different jobs. AVS compares the numeric portion of the billing address against the issuer’s record. That is a match check, not an authentication, and it says nothing about who is holding the card. Multi-factor authentication and 3-D Secure put a challenge in front of the person completing the order.
#2 | Employ Fraud Prevention Tools
Use a variety of fraud prevention tools, such as geolocation tracking, IP address monitoring, and device fingerprinting, to identify suspicious transactions and detect potential fraud. Ensure that these are deployed as part of a multifaceted, multilayer strategy.
#3 | Monitor Transactions
Regularly review transactions for signs of address fraud, including multiple orders to the same address, mismatched billing and shipping addresses, or unusually large orders. Keep tabs on new developments in fraud trends and behaviours.
#4 | Establish Clear Policies
Develop clear policies for handling returns, refunds, and chargebacks to minimize the risk of fraud. Ensure that these policies are followed closely, yet are flexible enough that they can be adapted to individual customers’ needs.
What Should You Do When a Customer’s Address Changes?
An address change on a customer account, followed shortly by an order, is the loudest pre-transaction signal most CNP storefronts collect and never act on. The question is not whether to treat it as suspicious. The question is what it actually tells you, and how wide a gap makes it stop mattering.
Here is what each of the common address signals covers, and what it leaves open.
| Signal | What it catches | What it does not catch | Reasonable response |
| AVS mismatch | A billing address the fraudster is guessing at | A fraudster who has the genuine billing address, which is most of them | Review, not decline. On its own it is a weak signal |
| Account address changed before the order | Account takeover, and mail redirection in progress | A customer who has genuinely moved, which is far more common | Hold the first order after the change. Re-authenticate through a channel the account did not just change |
| Shipping address seen on other accounts | Drop addresses and mail forwarding services | A shared household, an office, a student address | Review across the cluster rather than the single order |
| Shipping address is a mail forwarding service | Reshipping and interception routes | A customer who legitimately uses one, including expats and travellers | Restrict to billing address, or require signature on delivery |
| Billing and shipping do not match | Very little on its own | Gifts, corporate delivery, and anyone in the middle of moving | Weight it, do not act on it alone |
Two rows deserve a note, because they are the ones I see weighted wrongly most often.
An address change followed by an order within hours is a very different signal from an order that follows three weeks after an address change. But most fraud rules do not separate them. And re-authenticating through the email or phone associated with the account is worth nothing if the account takeover also compromised the email or phone (which it usually did).
The criterion is the gap between the change and the order, weighed against what a wrong decision costs you. A merchant declining on every address change is buying fraud coverage with false declines, and below a certain order value that trade loses money. That is the trade-off, and where it flips depends on your own average order value and abandonment rate, not on anyone else’s fraud rate.
Need More Help?
Address fraud reaches you as a clean order and leaves as a chargeback, which means most of what you can do about it happens before the goods move. Not all fraud comes from conventional, third-party criminal sources, though. That’s why we also strongly recommend seeking professional assistance to handle more difficult-to-manage loss sources, like friendly fraud.
Chargebacks911® works with merchants on both halves of that problem: the checks at the front end, and the disputes that arrive anyway. If you want to know what the two are costing you right now, contact us for a no-obligation ROI analysis.
FAQs
Can someone commit fraud with your address?
Yes. Address fraud is a type of identity theft that occurs when a fraudster uses someone else’s address, or uses a fake address, to facilitate illegal activities. This can include obtaining credit, goods, or services under false pretences, or it can be used to facilitate other criminal activities.
What to do if your address is being used for fraud?
Report it to the US Postal Inspection Service, which handles mail fraud and fraudulent change of address filings. You should also report it to the FTC at IdentityTheft.gov. Next, any letters or packages received under someone else’s name should have “not at this address” written on them clearly before they are returned to the post office.
What is an example of address fraud?
For example, package interception fraud occurs when a criminal uses a stolen credit card to make online purchases and then ships the goods to the victim’s address. The perpetrator then intercepts the packages before the victim becomes aware of the unauthorised transaction. In some cases, the criminal may ask the victim to forward the package to another address, making the victim an unwitting accomplice in the fraud.
Is it illegal to say you live somewhere you don't?
Not by itself. Post office boxes, commercial mailboxes, mail forwarding, and c/o arrangements are all lawful ways to receive mail somewhere you do not live. It becomes a crime when the false address is part of a scheme to defraud, which is what the federal mail fraud statute covers. It is also a crime where a statute requires true residency, as voter registration and driver licensing do.
How can you tell if an order is using a stolen address?
Often you cannot, from the order alone, because a stolen address is a real address and it passes the checks built to find a false one. What you can see is the context around it: a recent change to the account’s address, a shipping address that has appeared on unrelated accounts, or a delivery point that resolves to a mail forwarding service. Those are the signals worth building a rule on.