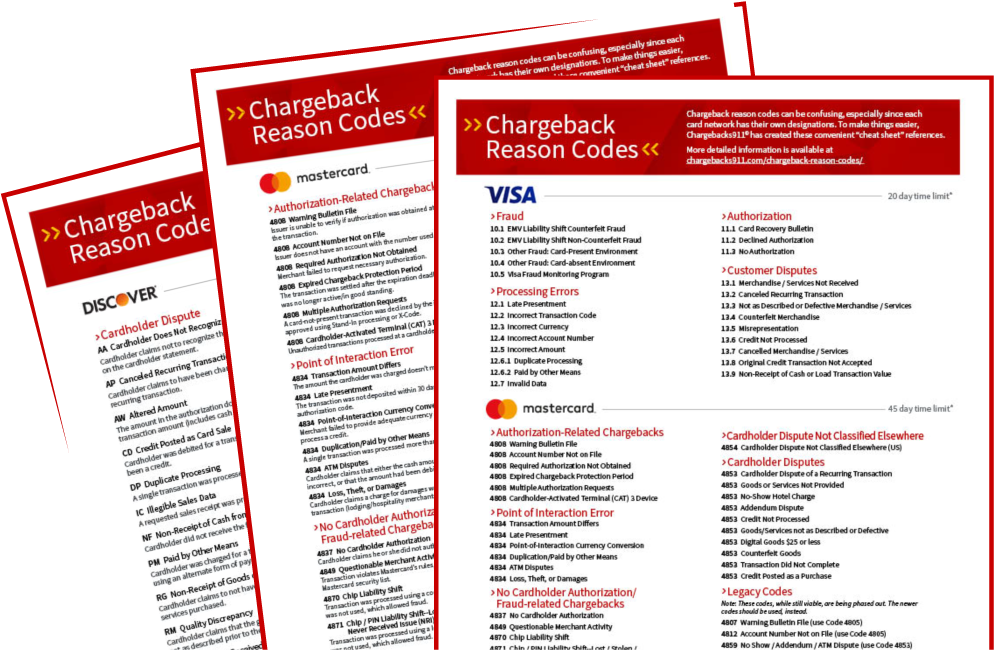



Navigating chargebacks issued using Mastercard reason code 4834 presents some obvious challenges.
First, there’s the opacity. Reason code 4834 can be issued with several different descriptors related to point-of-interaction errors. That could leave you wondering about the chargeback’s precise meaning and implications, and how to protect your business against the financial consequences.
In this piece, we dive into the essentials of Mastercard chargeback reason code 4834 — Improper Merchant Surcharge. Hopefully, I can shed some light on what this code signifies and offer practical guidance on identifying the root cause. Then, armed with this knowledge, you can take steps to address the issue and avoid future issues.
This reason code does not apply in all markets. It can only be applied to transactions carried out in the Canadian, Intra-European and Inter-European markets
Recommended reading
- Chargeback Legal Process: Is There a Step After Arbitration?
- How to Identify & Prevent Shipping Scams in 2026
- Chargeback Stats: All the Key Dispute Data Points for 2026
- PlayStation Chargebacks: Why Sony Suspends PSN Accounts
- Web Authentication API: WebAuthn, Passkeys & Merchant Login
- NEW DATA | FI Risk Resulting From Visa VAMP Requirements
What is Reason Code 4834 — Improper Merchant Surcharge?
Let’s say you get a chargeback with reason code 4834, and the description is “Improper Merchant Surcharge.” As you might’ve guessed, it means the bank is alleging that you applied an improper surcharge to the total amount of a purchase.
It could be that the additional fee was not allowed under Mastercard network rules. Or, that it was not properly disclosed to the cardholder. Either way, the issuer is indicating that the surcharge was the central issue, rather than other potential problems like an incorrect account number or late presentment.
What Caused This Dispute?
There are a few situations in which a bank might slap you with one of these chargebacks. Some common triggers include:
How to Respond to Mastercard Reason Code 4834 — Improper Merchant Surcharge
Alright, so you’re confident that you followed all relevant Mastercard guidelines… but you still got hit with one of these chargebacks. If you suspect the chargeback was issued as an error, you have the option to challenge it through the representment process.
Representment provides an opportunity to recoup funds lost to a disputed transaction, but it comes with strict time requirements. The window to assemble and deliver your representment case is typically limited to 45 days. But, this timeframe may be further constrained by your payment processor's internal procedures.
Your acquiring bank needs sufficient time to review and process your documentation. In the end, you may have only a matter of a few days to finalize your submission.
Furnishing the issuing bank with comprehensive documentation is essential. You need to gather compelling evidence that validates the original transaction and directly addresses the chargeback reason cited. The more pertinent and persuasive your documentation, the stronger your case will be.
Upon submission, the issuer will scrutinize your materials against the cardholder's claim. Based on their assessment, they will determine whether to overturn the chargeback in your favor or uphold the dispute.
Learn more about representment
Acceptable Evidence for Mastercard Reason Code 4834 — Improper Merchant Surcharge
Mastercard is not just going to take your word for it. If you want to submit a response, you’ll need evidence.
You need documentation proving that the transaction in question was not fraudulent. This may include:
- A copy of your policies, outlining surcharge practices, the surcharge percentage, applicable conditions, and any exemptions.
- Photos or screenshots that show you disclosed the surcharge policy at the physical point of sale, or on your site before checkout.
- A copy of the original transaction receipt, which should itemize the purchase amount, surcharge fee, and total charge separately.
- Any correspondence between you and the cardholder that discusses the surcharge, or which shows the cardholder's consent to pay it.
Alternately, if you’ve already processed a refund for the disputed surcharge amount, you can provide documentation like a refund receipt or transaction report to show that the cardholder has been reimbursed.
Remember: precise documentation is crucial when submitting your representment case. Keep the following guidelines in mind to help you assemble a compelling package:
- Prioritize clarity and brevity in your presentation. You want to make it quick and easy to understand everything.
- Emphasize critical information within your supporting documents to streamline the review process.
- Establish a logical structure and labeling system for each piece of evidence. Don’t make the issuer work to read your response.
- Provide a succinct narrative that connects your documentation to the specific chargeback reason code.
- Exclude any extraneous or duplicate materials that may detract from your core arguments.
By focusing on these key principles, you can create a well-organized and persuasive representment case that maximizes your chances of successfully overturning the chargeback.
How to Prevent Reason Code 4834 — Improper Merchant Surcharge Chargebacks
While representment is vital, it's even more critical to proactively prevent chargebacks. Here are steps to avoid chargebacks due to reason code 4834 — Improper Merchant Surcharge:
Have Additional Questions?
Handling chargebacks is a daunting task.
Esoteric reason codes, tight response timelines, and a convoluted chargeback process can lead to headaches, frustration, and wasted time. So… why fight chargebacks alone?
Chargebacks911®’s all-in-one prevention, management, and representment solution helps merchants fight first-party fraud, battle chargebacks, and recover revenue. Get in touch with us today for a complimentary ROI analysis.